The Final Mile Problem: How Gulf Delivery Infrastructure Is Quietly Undermining US Exporters' Customer Experience
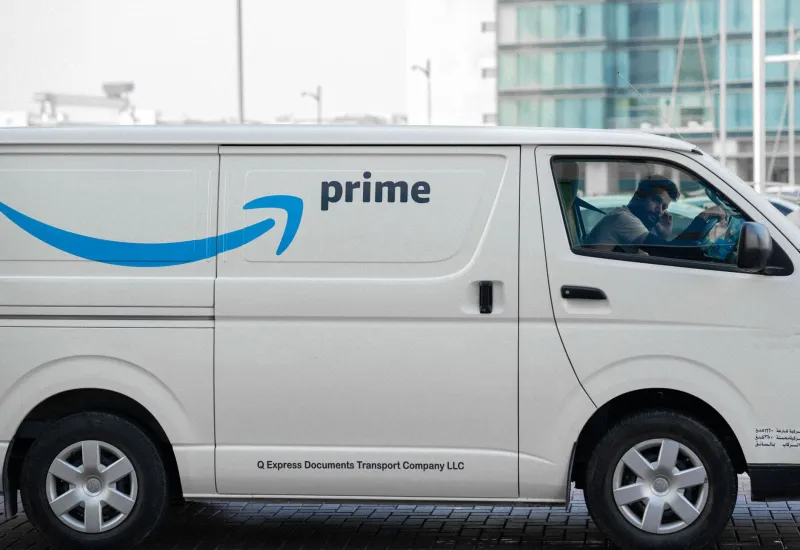
For most American companies entering Gulf markets, the strategic focus lands squarely on the big-ticket logistics challenges: ocean freight contracts, port clearance at Jebel Ali, customs documentation, and warehouse placement across the UAE or Saudi Arabia. These are legitimate concerns, and they demand real attention. But there is a quieter, less glamorous problem waiting at the other end of the supply chain—one that is eroding customer relationships and generating costly return cycles before many US exporters even realize what is happening.
Last-mile delivery in the Gulf does not work the way it does in the United States. That simple fact, routinely underestimated by American businesses, is responsible for a disproportionate share of fulfillment failures across the region.
A Courier Ecosystem Built on Fragmentation
In the United States, companies can rely on a handful of dominant national carriers—UPS, FedEx, USPS, Amazon Logistics—to move packages from distribution centers to doorsteps with a reasonable degree of consistency. Tracking is standardized. Delivery windows are predictable. Customer service escalation paths are well established.
The Gulf courier market operates on an entirely different structural logic. The region is served by a patchwork of local, regional, and international operators whose service quality, geographic coverage, and technological sophistication vary enormously. A courier that performs reliably within Dubai may have no meaningful presence in Sharjah, Ajman, or the Northern Emirates. A provider dominant in Riyadh may be ill-equipped to handle deliveries in secondary Saudi cities like Tabuk or Hail. No single carrier offers the kind of seamless national coverage that American companies take for granted at home.
For US exporters managing fulfillment from a centralized Gulf warehouse, this fragmentation creates an immediate operational problem. Selecting a single courier partner is rarely sufficient. Building a carrier matrix—tiered by geography, delivery speed, and product category—requires local knowledge that most American companies simply do not have when they first enter the market.
The Address Problem No One Warned You About
Perhaps the most disorienting challenge for US logistics teams is the absence of standardized addressing conventions across much of the Gulf. While the UAE has made meaningful progress in recent years through initiatives like Abu Dhabi's Onwani system and Dubai's expanding postal code framework, large portions of the region still operate without formal street addresses in the Western sense.
In practice, this means that delivery instructions frequently rely on landmarks, building descriptions, and neighborhood references that are intelligible to local residents but opaque to routing algorithms designed for structured address databases. A shipment destined for a residential compound in a Saudi city may carry directions that read more like verbal navigation instructions than a standardized postal address.
For US companies whose warehouse management systems and logistics software were built around ZIP codes and structured address fields, this creates a genuine technical incompatibility. Orders fail to route correctly. Delivery attempts are made to wrong locations. Packages are returned to sender after multiple failed attempts, generating reverse logistics costs and, more damaging still, customer frustration.
Adapting to this reality requires more than a software patch. It demands a fundamental rethinking of how customer address data is collected at the point of sale, how that data is interpreted by fulfillment teams, and how courier partners are briefed on delivery instructions.
Geographic Realities That Defy American Assumptions
The physical geography of the Gulf introduces logistics challenges that have no direct American equivalent. Extreme summer temperatures—regularly exceeding 110 degrees Fahrenheit across much of the region—create serious constraints for temperature-sensitive products and place unusual demands on delivery vehicles and storage facilities. Construction activity in rapidly developing urban areas frequently disrupts established delivery routes. Gated residential communities and high-security commercial compounds require advance coordination that adds friction to standard delivery workflows.
Beyond urban centers, the challenges intensify. Serving customers in remote areas of Saudi Arabia, Oman, or the UAE's interior requires either partnerships with specialized rural couriers or acceptance of significantly extended delivery timelines. For US companies accustomed to promising two-day or next-day delivery as a competitive baseline, recalibrating customer expectations for Gulf markets is both a marketing challenge and a logistics reality.
What Delivery Failures Actually Cost
The financial consequences of last-mile failures extend well beyond the direct cost of a returned shipment. In a region where word-of-mouth reputation and social media visibility carry outsized commercial weight, a pattern of delivery failures can damage brand perception faster than almost any other operational shortcoming.
Gulf consumers—particularly in the UAE and Saudi Arabia, where e-commerce adoption is among the highest in the world—have developed sophisticated expectations around delivery quality. They compare their experiences against regional benchmarks set by Amazon.ae, Noon, and other platforms that have invested heavily in last-mile infrastructure. When an American brand falls short of those benchmarks, the reputational cost accumulates quickly.
Return logistics compound the problem. Processing returned goods from Gulf customers back through the fulfillment chain involves customs re-entry considerations, restocking costs, and coordination with courier partners who may not have robust reverse logistics capabilities. US companies that have not built these workflows into their Gulf operations often find that returns become a financial drain that was never modeled into their market entry projections.
Building a Resilient Gulf Fulfillment Network
Addressing the last-mile problem requires a layered strategy rather than a single solution. Several principles have proven effective for US companies that have successfully navigated these challenges.
First, invest in local courier intelligence before committing to carrier contracts. Conducting structured evaluations of courier performance across the specific geographies where your customer base is concentrated—rather than relying on a carrier's self-reported coverage claims—provides a far more accurate picture of operational reliability.
Second, build address validation and enrichment into the customer experience from the point of order. Working with regional technology partners who understand Gulf addressing conventions can help translate customer-provided location data into formats that courier routing systems can process accurately.
Third, establish clear delivery expectation frameworks that reflect Gulf realities rather than importing American standards wholesale. Customers who receive accurate delivery windows are significantly more forgiving of longer timelines than customers who were promised speed that the infrastructure cannot deliver.
Finally, treat last-mile logistics as a strategic investment rather than an operational afterthought. The US companies finding durable commercial success in Gulf markets are those that recognized early that the final mile is not a commodity function—it is a direct expression of brand promise in a market where the competition for customer loyalty is intense and the cost of losing it is high.
The Gulf's logistical frontier is not at the port. It is at the doorstep. American exporters who build their market expansion strategies around that understanding will be far better positioned to convert initial sales into lasting customer relationships.